FEMA Flood Aid vs. Flood Insurance: What Homeowners Get
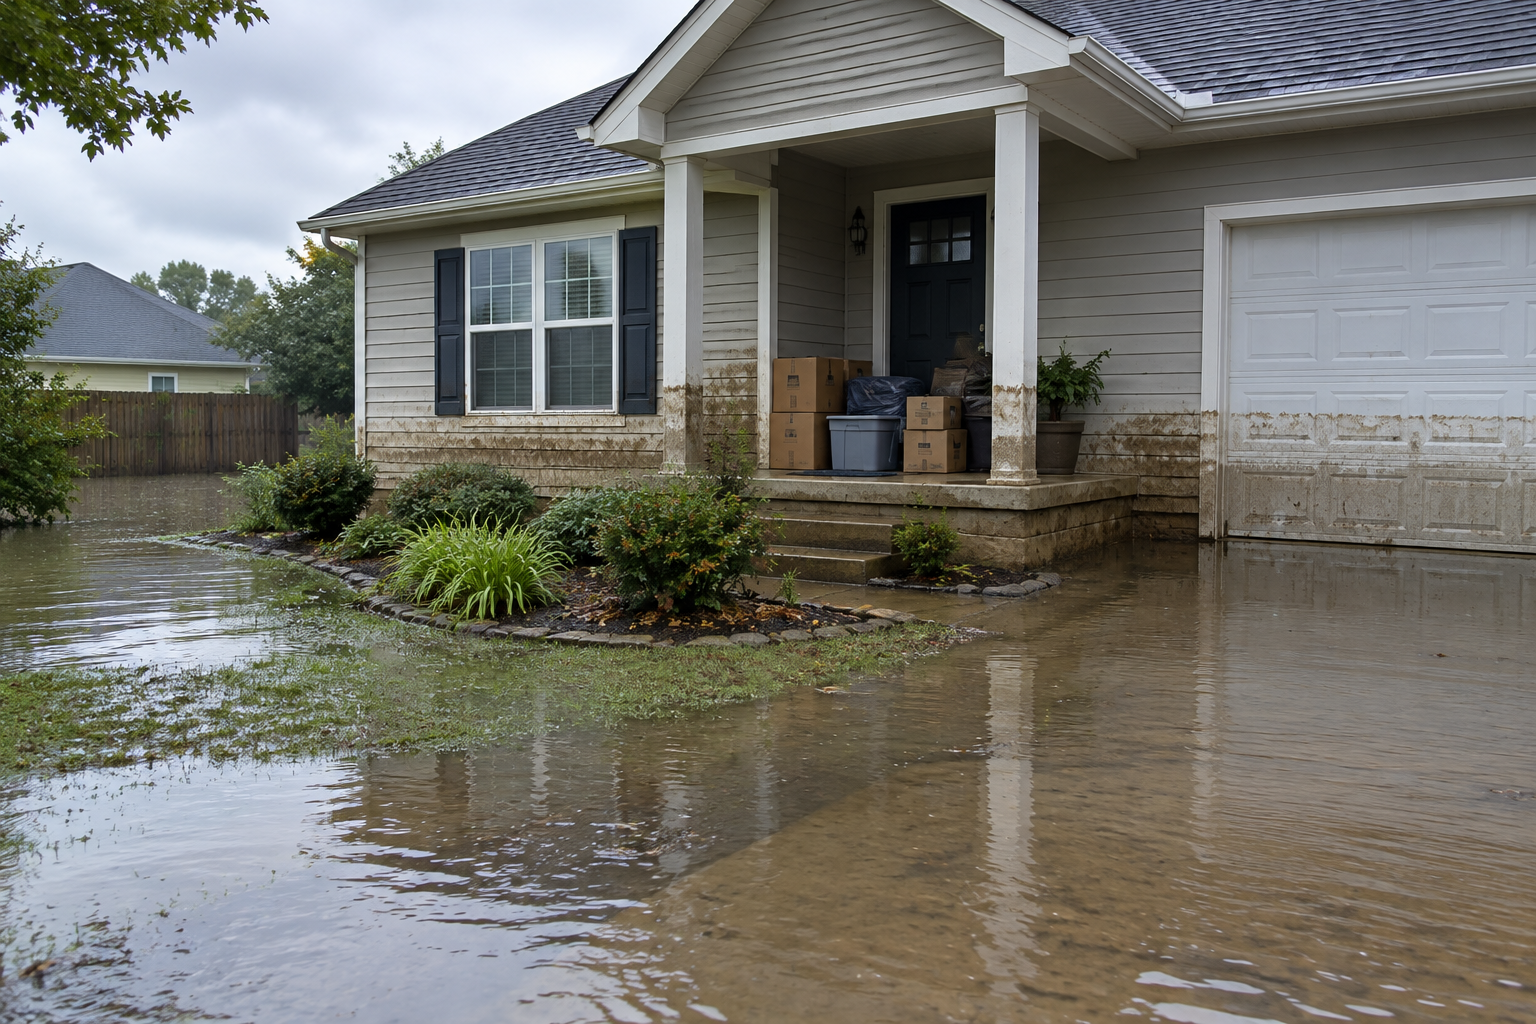
A presidential disaster declaration does not create an automatic, full-cost rebuilding fund for every flooded home. FEMA administers two very different forms of federal help: disaster assistance for eligible households after certain declared disasters, and the National Flood Insurance Program, or NFIP, which is a separate insurance program purchased before a loss.
Call for a free estimate:
The difference determines what money may be available, when it becomes available, and which records you need. Disaster assistance can address qualifying unmet needs, but it is designed as a safety net. Flood insurance is the coverage intended to insure eligible building damage, contents damage, or both under the policy you bought.
What does FEMA actually provide after a flood?
FEMA may provide limited disaster assistance only after the federal government declares a disaster and a household meets the program’s eligibility rules. According to FEMA’s Individual Assistance Program, its Individuals and Households Program can provide financial assistance and direct services for uninsured or underinsured necessary expenses and serious needs.
That program is not the same as an NFIP claim. Individual Assistance is tied to a specific declared event and an application review. It does not turn every flood loss into a federally funded restoration project, and it does not duplicate money available from insurance or another source.
NFIP coverage works differently. FEMA manages the program, while more than 47 insurance companies and NFIP Direct deliver policies to the public. The policyholder reports a covered flood loss through the insurance process, subject to the policy’s terms, deductibles, limits, and documentation requirements.
Most standard homeowners insurance policies do not cover flood damage, according to FEMA’s flood insurance guidance. A burst pipe or wind-driven rain may be handled under different coverage rules, but rising water that meets the policy definition of flood requires separate flood coverage. The cause of water damage matters as much as the visible damage.
Why will disaster aid rarely fund a complete restoration?
Federal disaster assistance is intended to address essential, eligible needs after a declared disaster, rather than replace every damaged item or restore a house to its previous condition. FEMA’s program description expressly limits assistance to uninsured or underinsured necessary expenses and serious needs, so insurance payments, voluntary aid, and other benefits affect what assistance may remain available.
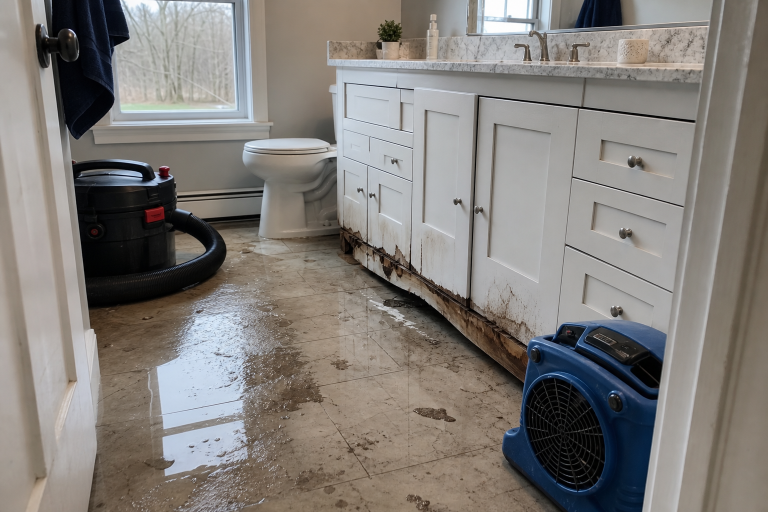
A household can therefore have real flood damage and still receive less federal aid than the total restoration estimate. Flooring, cabinets, wall finishes, appliances, furniture, landscaping, upgrades, and temporary living costs do not become fully funded simply because a disaster has been declared. Eligibility, the type of loss, insurance status, and program rules determine the result.
Insurance is also not a blank check. An NFIP policy can cover building property, contents, or both, depending on the coverage purchased. It does not automatically mean every expense connected with a flooded property will be paid. Homeowners should read their declarations page, identify whether it includes building and contents coverage, and ask the insurer for the applicable policy form when opening a claim.
When is flood insurance required?
Flood insurance is generally required for homes and businesses in high-risk flood areas when they have mortgages from government-backed lenders. FEMA states that this requirement applies in those circumstances, while flood insurance remains available to people in participating NFIP communities even outside the highest-risk areas.
A lender’s requirement is based on the property’s mapped flood risk and the type of loan. It is not a statement that flooding cannot occur elsewhere. FEMA’s guidance notes that floods can happen anywhere, which is why a homeowner outside a required area may still decide that a separate policy is worth considering.
Waiting until water is forecast is a poor substitute for advance planning. FEMA says an NFIP policy typically has a 30-day waiting period before it takes effect, with limited exceptions such as certain lender-required purchases or a flood map change. Review the timing before hurricane season, a property purchase, or a refinance rather than assuming coverage can be added at the last minute.
How should homeowners separate an insurance claim from FEMA assistance?
Start by identifying every potentially relevant claim route, then keep the records separate. An NFIP policyholder should contact the insurer or agent to report the flood loss. A household in a declared disaster area may also apply for FEMA assistance if it has uninsured or underinsured necessary expenses, but the FEMA application does not replace the insurance claim.
Do not withhold an insurance claim because you expect disaster aid to be faster or broader. FEMA’s rules against duplicating benefits mean the agency needs to understand what insurance may pay. An insurer’s settlement documents can therefore be central to the assistance review, particularly when a policy exists but does not fully address the claimed need.
Keep a single property file, but organize it by purpose. Make separate folders for insurer correspondence, FEMA application records, contractor estimates, photographs, receipts, and temporary-housing expenses. Clear records reduce the chance that an adjuster, caseworker, or contractor receives a partial or mismatched version of the same loss.
Before signing a restoration contract, compare its scope with the damage documentation and the money actually available. A vague proposal can create scope disputes later, especially when it does not state what demolition, drying, material removal, cleaning, repairs, permits, and finish work include. A detailed written scope is more useful than a low total with broad allowances.
Which documents should you keep after flood damage?
Proof of identity, occupancy, ownership, insurance status, and loss-related costs form the core record set for a FEMA application. FEMA’s required documents guidance explains that applicants may need to provide documents supporting identity, occupancy, or ownership when the agency cannot verify that information through its normal process.
The exact request depends on the application and the information FEMA can verify. Keep originals when possible and send copies only through the agency’s stated process. A utility bill, lease, deed, mortgage statement, property tax record, insurance declaration, settlement letter, or receipts may establish different facts, so a document that proves one issue may not prove another.
- Photograph each affected room and exterior area before debris removal, then photograph damaged major items individually when practical.
- Save repair estimates, invoices, receipts, insurer letters, claim numbers, and records of payments from any source.
- Record dates, names, and short summaries for calls with insurers, FEMA, lenders, and contractors.
- Keep copies of documents that show you occupied or owned the home at the time of the disaster.
- Ask a contractor to separate emergency stabilization from permanent repairs, rather than accepting one unexplained total.
Photos and receipts are especially useful when they tie a cost to a specific damaged area or item. They do not guarantee payment, but they make it easier to show what was damaged, what work was proposed, and what you paid.
Call for a free estimate:
What should happen before permanent repairs begin?
Documenting the condition and confirming the claim process should come before non-emergency restoration work. Necessary steps to protect the property may be time-sensitive, but throwing away damaged materials or completing major repairs before the insurer has had a chance to evaluate the loss can make the claim record harder to establish.
Ask the insurer what it needs before authorizing a full rebuild. Then request written estimates that distinguish cleaning and removal from replacement work. If a contractor proposes upgraded materials, have that upgrade priced separately from a like-for-like repair so you can see what insurance or aid may not cover.
Water that reached HVAC equipment deserves separate attention. Rather than restarting or opening equipment yourself, review Abodence’s flood safety checks before restarting HVAC and arrange an appropriate professional assessment when equipment may have been affected.
How can you make a realistic flood recovery plan?
A realistic plan begins with confirmed coverage and documented needs, not a hoped-for grant amount. List the immediate work needed to protect the building, the insured work supported by the policy, expenses that may be eligible for FEMA review, and upgrades you would pay for yourself. This separates recovery necessities from elective improvements.
Use the insurer’s claim communications and a contractor’s itemized scope to identify gaps. If flood coverage was not in place, FEMA assistance may still be available after an eligible declaration, but it should be treated as limited support subject to approval, not as a replacement for a policy. If an NFIP policy was in place, do not assume its building coverage also includes personal property unless the declarations page says so.
For future risk planning, inspect the house beyond the rooms that visibly flooded. Moisture in attic spaces can also create persistent property problems, and Abodence’s guide to attic moisture warning signs and ventilation fixes explains what conditions merit closer attention.
For a property-specific restoration scope, ask a licensed restoration contractor for a written assessment and quote that clearly separates emergency work, repair work, and any optional upgrades. For a free, no-obligation discussion please call a listed specialist.
FAQ
Does FEMA automatically pay to rebuild a flooded home?
No. FEMA disaster assistance is available only after an eligible federal disaster declaration and an application review, and it addresses qualifying uninsured or underinsured necessary expenses and serious needs rather than automatically paying a home’s full rebuilding cost.
Is FEMA flood assistance the same as flood insurance?
No. FEMA manages the NFIP, which provides separately purchased flood insurance, while FEMA’s Individual Assistance Program may offer limited disaster help after certain declared events. An NFIP claim depends on the policy in force before the flood, while disaster assistance depends on declaration and eligibility rules.
Do homeowners policies usually cover flooding?
Generally, no. FEMA states that most homeowners insurance does not cover flood damage, so homeowners should review their own policy and consider separate flood insurance if they want coverage for flood losses.
What paperwork can FEMA ask for after flooding?
Applicants may be asked for records that establish identity, occupancy, ownership, insurance information, or disaster-related costs. FEMA requests documents when it cannot verify needed information, so keep copies of housing records, insurance correspondence, receipts, estimates, and damage photos.
Can you apply for FEMA help if you have flood insurance?
Yes, an insured household may apply after an eligible declaration, but FEMA does not duplicate insurance benefits. Report the insurance claim promptly and retain settlement, denial, or coverage documents so the agency can evaluate any remaining eligible unmet need.